
Before You Spend Your Holiday Bonus, Build Your Emergency Fund First
The holiday season is approaching, which means many Filipino employees are looking forward to receiving their 13th month pay and year-end bonuses. While it can be tempting to spend this extra income on Christmas presents, holiday getaways, or the latest gadgets, there’s another financial priority worth considering: building your emergency fund.
For young professionals and first-time earners, saving for unexpected expenses may not seem as exciting as enjoying the rewards of a year’s hard work. However, setting aside even a portion of your bonus can help you prepare for financial challenges without relying on loans or borrowing money.
According to Metrobank’s financial education program, Earnest, an emergency fund is money reserved specifically for unforeseen and urgent expenses. It should remain separate from your budget for shopping, vacations, and other nonessential purchases.
Think of it as a financial safety net. You may not need it today, but having savings readily available can make a significant difference when an unexpected expense disrupts your budget.
Before spending your year-end earnings, consider these five practical ways to get your emergency fund started.
1. Give Your Holiday Budget a Little Breathing Room
The Christmas season comes with plenty of expenses, from family reunions and exchange gifts to holiday dinners and spontaneous shopping trips. Without a spending plan, these seemingly small purchases can quickly consume your 13th month pay.
To avoid overspending, establish your holiday budget before making purchases. Determine how much you want to spend on celebrations and gifts, then decide how much of your additional income you can dedicate to savings.
You don’t need to put your entire bonus into your emergency fund. Setting aside a manageable portion while leaving enough for your holiday plans can help you enjoy the season without sacrificing your financial goals.
If you aren’t receiving extra income this year, don’t let that stop you from saving. Start with whatever amount your regular budget allows. Consistent contributions, even small ones, can help you develop better money management habits over time.
2. Start With What You Actually Spend
How much should you save for emergencies? The answer depends on your lifestyle, financial obligations, and monthly expenses.
Instead of copying another person’s savings target, calculate how much you need to cover your essential costs. Include necessities such as groceries, transportation, rent, utilities, and any financial contributions you make to your household.
Living with your parents doesn’t mean you have no expenses to consider. If you regularly contribute to groceries, pay household bills, or help support your family, include those costs in your calculations.
Once you understand your monthly financial commitments, set an initial savings target that feels achievable. You can increase it as your income grows or your responsibilities change.
As a general guideline, single individuals without dependents may aim to save enough to cover six to 12 months of their average daily expenses. Married individuals and those with dependents may consider building a reserve equivalent to 12 to 24 months of their average living expenses.
Remember, you don’t need to reach your ultimate savings goal before the holidays. Focus on establishing a foundation and gradually building your financial cushion.
3. Remember: “Sayang ang Sale” Isn’t an Emergency
Online shopping promotions and limited-time discounts can make spending feel irresistible, especially during the holiday season. However, a great deal doesn’t automatically qualify as a financial emergency.
Before withdrawing money from your emergency fund, evaluate the situation. Is the expense unexpected, urgent, and unavoidable? If it doesn’t meet these criteria, you may need to reconsider using your savings.
Unexpected medical bills and sudden income loss are examples of situations where an emergency fund can help. Concert tickets, new holiday clothes, and an upgrade to your favorite gadget, on the other hand, should be covered by a separate budget.
If there’s something you’ve been wanting to buy, create a dedicated savings goal for it instead of dipping into your emergency reserves. This approach allows you to enjoy your purchases while keeping money available for genuinely urgent needs.
4. Make Saving a Payday Habit
Have you ever received your salary, paid a few bills, and wondered how your money disappeared so quickly? Without a consistent savings routine, it’s easy to spend first and save whatever remains.
One way to address this is to treat your emergency fund contribution as a regular financial obligation. As soon as your salary arrives, transfer a predetermined amount into savings before allocating the rest to discretionary spending.
Choose a contribution that fits comfortably within your budget after accounting for bills, necessities, and other commitments. You can start small and adjust your contributions whenever your financial situation changes.
The key is consistency rather than the amount you save in a single month. By making saving part of your payday routine, you can continue building your emergency fund long after the holiday season ends.
5. Give Your Emergency Money Its Own Space
When your everyday spending money and emergency savings sit in the same account, it can be difficult to tell how much you can actually afford to spend. A separate savings account helps create a clear distinction between money available for daily purchases and funds reserved for unexpected expenses.
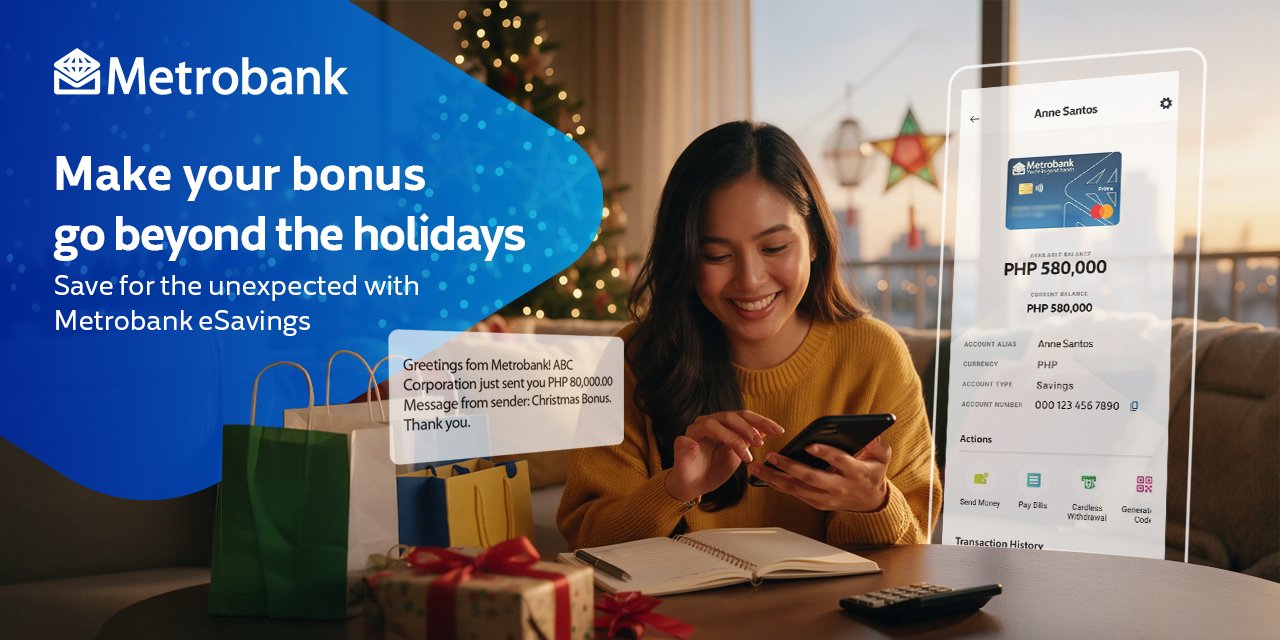
Metrobank eSavings provides a convenient option for opening and managing a savings account, allowing you to give your emergency fund a dedicated place to grow. Keeping these funds separate can also help you resist the temptation to spend your savings on unnecessary purchases or budols.
Of course, an emergency fund is meant to be used when a genuine need arises. If you have to withdraw money to cover an unexpected expense, don’t feel discouraged. Once your finances stabilize, work toward replenishing the amount you used.
Put Your Future Self on Your Holiday Gift List
The holidays are a time for giving, celebrating, and rewarding yourself for your hard work. But while you’re preparing gifts for the people you care about, remember to make room for your own financial well-being.
Your 13th month pay and holiday bonus can help you enjoy the season while taking meaningful steps toward financial security. Even a modest contribution to your emergency fund can be a starting point for preparing for unexpected expenses.
Ready to take the first step? Start building your savings with Metrobank eSavings. Download the Metrobank app and prepare one valid ID to begin your savings journey in minutes.*
For now, Metrobank eSavings is available for new depositors only.